Kia EV Registrations Rise 24% in August as Syros Offsets Clavis Decline
Kia’s August EV registrations rose to 753 as Syros offset a monthly decline in Clavis. The breakdown reveals a higher base-variant share for Clavis, contrasting with battery mixes and low EV6 and EV9 volumes.
Category:
Tag:
- Kia
- Syros EV
- Carens Clavis EV
- EV6
- EV9
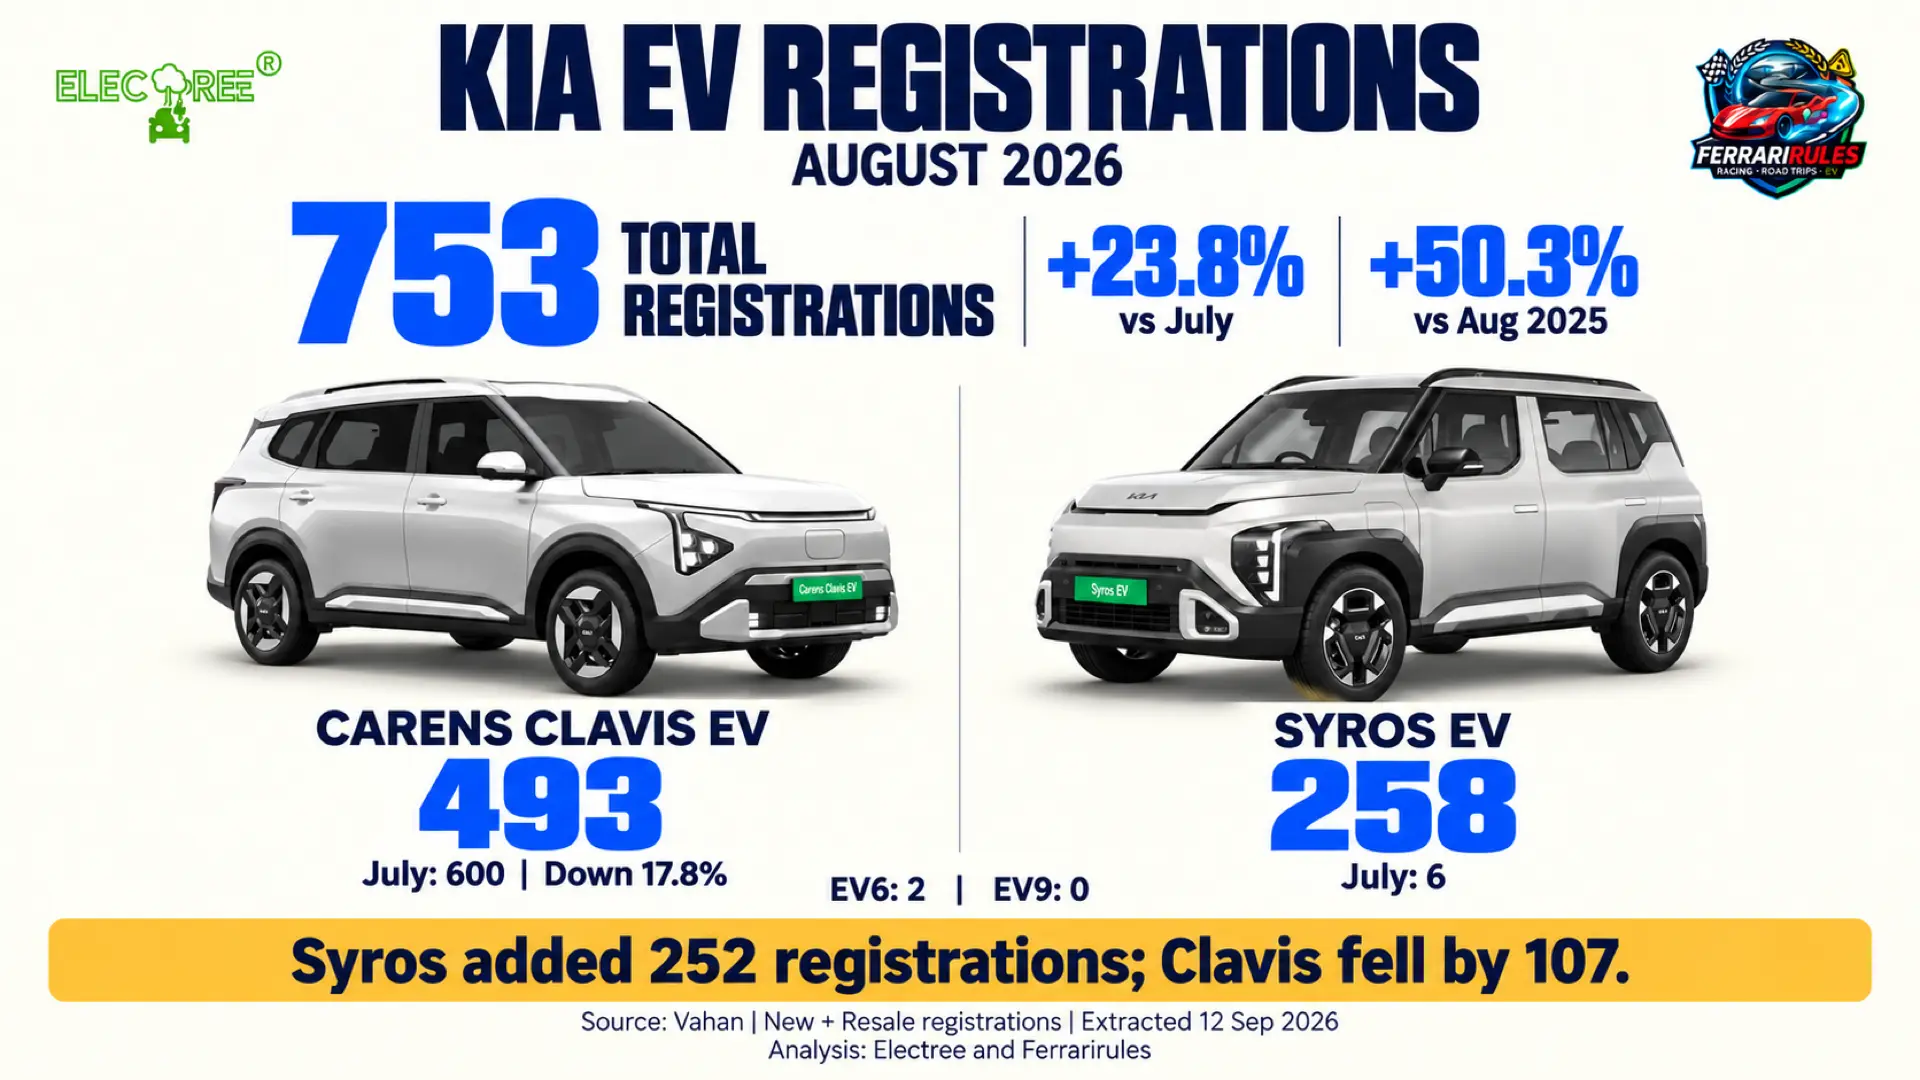
Kia recorded 753 EV registrations in August 2026, up 23.8% from July and 50.3% year on year. Syros supplied the additional volume that lifted Kia’s total, more than offsetting a monthly decline in Carens Clavis EV registrations.
The improvement was concentrated in the newly introduced model. Clavis remained Kia’s largest EV, but its registrations fell month on month, while EV6 and EV9 together contributed just two registrations. Within Clavis, base variants held their volume as mid and top variants weakened.
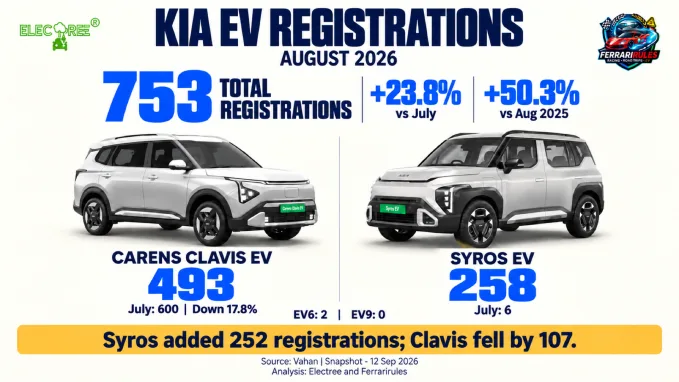
Kia August EV registrations by model
Model | July 2026 | August 2026 | Change |
Carens Clavis EV | 600 | 493 | −17.8% |
Syros EV | 6 | 258 | +252 units |
EV6 | 2 | 2 | Unchanged |
EV9 | 0 | 0 | Unchanged |
Total | 608 | 753 | +23.8% |
Syros contributes 258 registrations in August
Syros recorded 258 registrations in August, compared with six in July. Its 252 additional registrations more than covered Clavis’s 107-unit decline, leaving Kia with a net monthly increase of 145. Syros accounted for 34.3% of the August total.
Syros launched in July 2026 with deliveries starting in August.
Clavis falls monthly but remains ahead of last August
Clavis registrations declined from 600 in July to 493 in August, a fall of 17.8%. Against 459 in August 2025, however, the model was up 7.4%.
Clavis launched in July 2025. Its August 2026 result was therefore ahead of the corresponding month a year earlier, even though it lost ground against July. That distinction matters: a monthly decline is not the same as a year-on-year contraction.
Clavis base variants gain share without adding volume
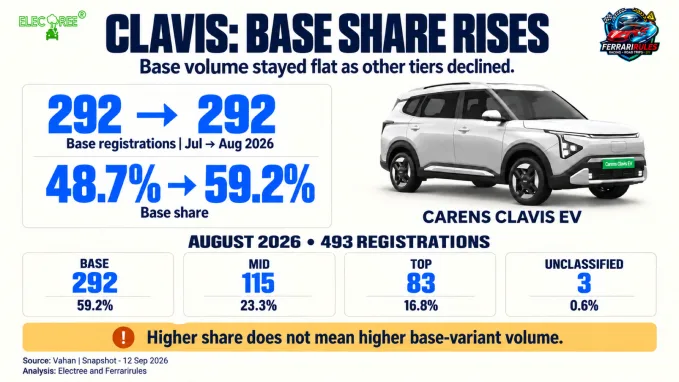
The most revealing Clavis result is the gap between share and volume. Base variants recorded 292 registrations in both July and August, but their share rose from 48.7% to 59.2% as other tiers weakened.
Mid variants fell 40.7%, from 194 to 115, while top variants declined 25.9%, from 112 to 83. The HTK+ alone recorded 269 registrations, or 54.6% of Clavis’s August total. HTM contributed the remaining 23 base-tier registrations.
The base variants’ higher share reflects resilience during a weaker month, not additional registrations. Treating the share increase alone as stronger demand would miss that distinction.
Smaller battery leads in Clavis, while a larger battery leads in Syros
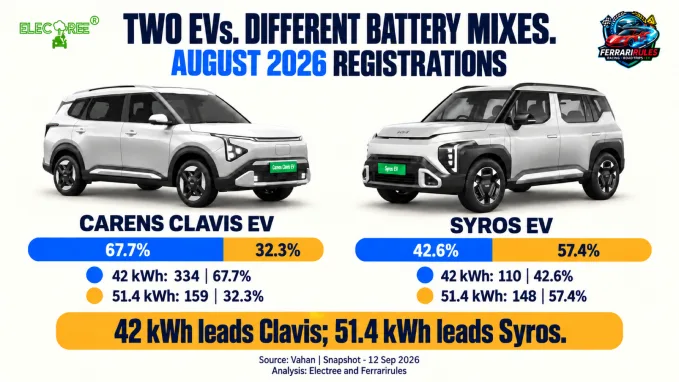
The 42 kWh pack accounted for roughly two-thirds of Clavis registrations. Its share increased from 62.5% in July to 67.7% in August, even as its volume fell from 375 to 334. Larger-pack registrations fell more sharply, from 225 to 159.
Syros showed the opposite split: 57.4% of registrations were classified with the 51.4 kWh pack. Its top variants contributed 113 registrations, or 43.8% of the model total, ahead of base variants at 77 and mid variants at 68. The HTX+ was its largest individual variant with 85 registrations.
The registration mix suggests different combinations are finding traction within each range. It does not establish why: pricing, vehicle availability, and delivery timing may all influence the recorded mix.
EV6 falls sharply while EV9 remains at very low volumes
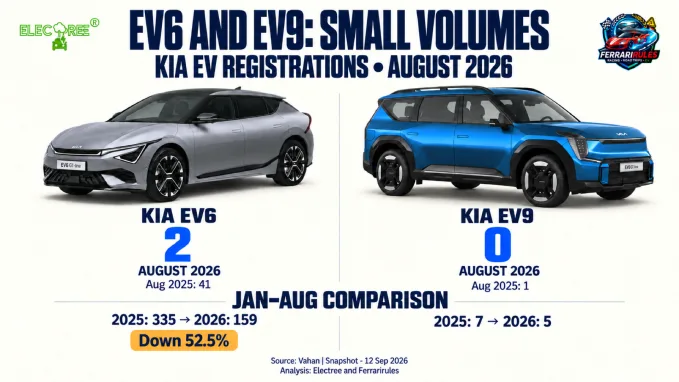
Kia’s overall EV growth does not extend to EV6 and EV9. Together, they recorded 164 registrations in January–August 2026, down from 342 a year earlier, a decline of 52.0%. Their combined share of Kia’s EV registrations fell from 41.7% to 4.0%, reflecting both their lower volumes and the expansion of Clavis and Syros.
EV6 recorded just two registrations in August, unchanged from July and down 95.1% from 41 in August 2025. Across January–August, its registrations fell from 335 to 159, a decline of 52.5%. The weak August count therefore sits within a broader year-to-date decline, rather than being an isolated monthly result.
EV9 recorded no registrations in either July or August in the supplied extract. Its January–August total was five, against seven a year earlier. At this scale, a difference of only two registrations is more informative than a large-looking percentage movement; monthly delivery timing can substantially affect the comparison.
What to watch next
August shows Syros adding to Kia’s EV total while Clavis remains ahead of its year-earlier volume despite a weaker month. Syros’s delivery start date and subsequent month registration volumes will be needed to assess its pace more fairly. The next question is whether Kia can build on both models together: sustain Syros’s initial registrations and stabilise Clavis’s mid and top variants.
Data and Methodology
Source and extraction date: Vahan data through 31 August 2026; snapshot taken on 12 September 2026. Scope: Kia EV registrations in August 2026, with comparisons to July 2026, August 2025, and January–August. Metric: New plus Resale registration transactions; not wholesale dispatches or exclusively new-vehicle sales. Coverage and exclusions: All available Vahan coverage with no additional state or registration-category exclusions.
References
Launch context: Kia announcement dated 15 July 2025 for Carens Clavis EV and Kia announcement dated 23 July 2026 for Syros EV.
Kia — https://www.kia.com/th/en/util/news/kia-carens-clavis-ev-2025.html
Kia brochures — https://www.kia.com/in/buy/download-brochure.html
Disclaimer: The values represented are new + resale vehicle registrations and not dealer dispatches, sourced via RTOs through Vahan. The data is exclusive to ElecTree and Ferrarirules. Republishing the data on any social media platform or forum without credit is prohibited and will amount to copyright infringement and may result in appropriate legal action.
To comment and participate in discussion Click Here
Recent Articles
Trending Articles
Kerala Makes EVs More Affordable: Revised Road Tax Structure to Accelerate Adoption
India Car Sales by Fuel Type — March 2026: EV Share Hits New High, CNG Surges, Petrol Loses Ground
No Fire Safety Certificate Will Be Declined Over EV Chargers, Says Haryana Fire Department
Haryana Releases Draft Fire Safety Guidelines for EV Charging