Top EV Two-Wheelers in India - August 2026
Analysis of India’s electric two-wheeler sales in August 2026. Discover how top platforms like the Bajaj Chetak C3 Series, TVS iQube, and Ather Rizta are reshaping the market and competing for dominance across family and utility scooter segments.
Category:
Tag:
- EV 2-wheelers
- EV Sales
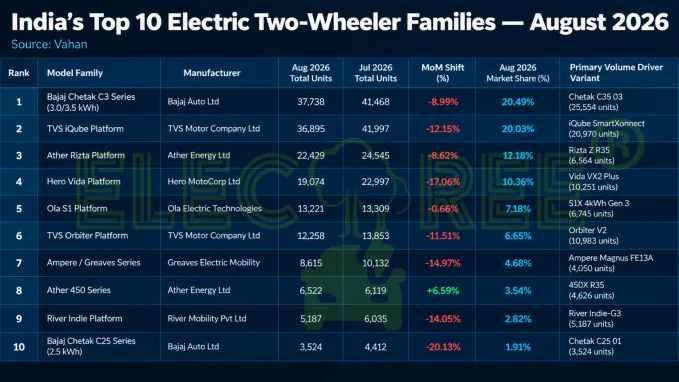
India’s electric two-wheeler market logged 184,198 total retail registrations in August 2026. While the overall market experienced a 10.45% month-on-month (MoM) consolidation from July's peak of 205,687 units, year-on-year (YoY) growth surged by 68.36% compared to August 2025 which stood at 109,408 units.
Driving this expansion is the battle among legacy manufacturers and EV startups, with a select group of flagship models commanding the majority of consumer demand. Leading the charge, the top three individual vehicle models accounted for nearly 31% of all electric two-wheelers sold nationwide, showcasing how targeted product positioning all across the range, from premium family commuters to sub-₹1 lakh utility scooters, is shaping market dominance. This list of top sales-performers is based off retail registration data from Vahan.
Top 3 Best-Sellers
1. Bajaj Chetak C3 Series
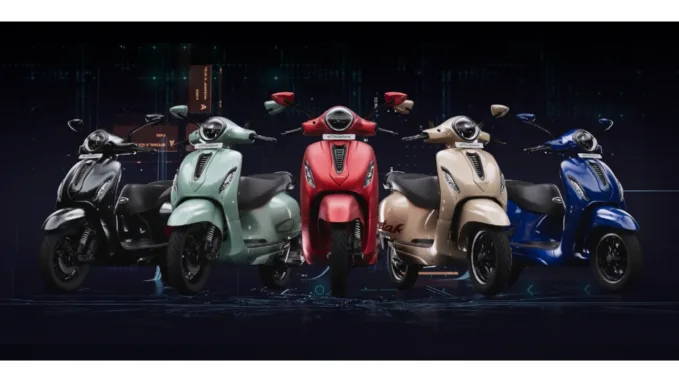
Bajaj Auto’s Chetak C3 Series, comprising its mid-tier and flagship 3.0 kWh and 3.5 kWh battery offerings, retained its position as India’s single best-selling electric two-wheeler platform in August 2026, registering 37,738 retail units (down 8.99% MoM from 41,468 units in July). By isolating the core C3 platform from the entry-level C25 series, the figures highlight how strongly Bajaj’s premium metal-body architecture resonates with mainstream buyers.
The core volume driver within this lineup remains the Chetak C35 03 (25,554 units), powered by an IP67-rated 3.5 kWh battery pack that delivers an IDC-certified range of 151 km paired with a 3.1 kW motor achieving top speeds of 63–70 km/h. Complementing the flagship C35 03 are secondary trims such as the C35 01 (4,620 units), C35 02 (4,466 units), and C30 01 (2,802 units). Equipped with full-color LCD digital consoles, turn-by-turn navigation, reverse assist, and hill-hold assist, the C3 series commands a 20.49% market share on its own, holding off strong competition from the TVS iQube and Ather Rizta.
2. TVS iQube
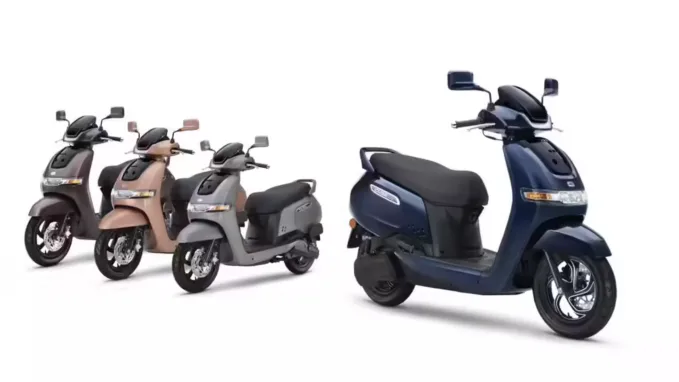
Securing the runner-up position, the TVS iQube platform recorded 36,895 retail sales in August 2026 (a 12.15% MoM dip from 41,997 units in July), capturing a 20.03% market share. TVS Motor Company specifically engineered the iQube series to bridge the transition for conventional ICE scooter owners by focusing on familiar upright ergonomics, neutral family styling, and ultra-reliable hardware rather than polarized, hyper-futuristic aesthetics.
The lineup is anchored by the high-volume iQube SmartXonnect variant (20,970 units), which features a 3.4 kWh lithium-ion battery pack paired with a quiet hub-mounted motor that yields an IDC-certified range of 145 km (~100 km real-world range). Its defining feature is a 7-inch TFT instrument cluster running TVS SmartXonnect software for live vehicle tracking, geofencing, crash alerts, turn-by-turn navigation, and call management. The broader iQube lineup also includes the entry-spec SmartXonnect 11 2.2 kWh trim (4,775 units), the long-range ST 17 trim (4,707 units), and the S15 trim (3,374 units). Positioned directly against the Chetak C3 and Ather Rizta platforms, TVS's vast dealer footprint and service network ensure the iQube line remains a cornerstone of the Indian EV market.
3. Ather Rizta
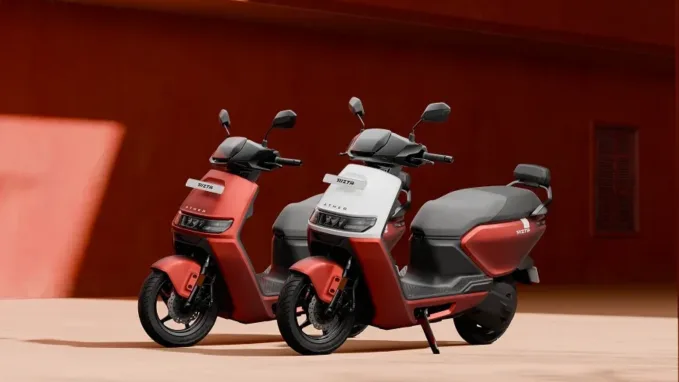
Rounding out the top three, the Ather Rizta platform registered 22,429 retail units in August 2026 (down 8.62% MoM from 24,545 units in July), securing a 12.18% market share. Ather Energy introduced the Rizta line specifically to capture practical suburban households requiring superior luggage capacity, wide dual seating, and active vehicle control safety tech and found their 450X/S offerings too sporty or impractical.
The platform is driven by two flagship configurations: the top-spec Rizta Z R35 (6,564 units) and the Rizta S FX09 (6,544 units), supported by the Rizta Z FX09 (4,254 units) and Rizta S R35 (4,012 units). Equipped with battery options up to 3.7 kWh (delivering an IDC range of 159 km), the Rizta introduced segment-first safety features including SkidControl traction control, Auto-Hold, FallSafe, and emergency stop signals. Its primary utility highlights include a massive 34-liter under-seat boot, an optional 22-liter flexible front frunk, and an ultra-wide long seat designed for maximum pillion comfort. Going head-to-head with the Chetak C3 and TVS iQube platforms, the Rizta has established itself as Ather’s primary growth engine. It will however be interesting to see if Aether newly announced Konark will cannibalize Rizta sales or capture a bigger market share for Aether.
The Remaining Top-10 Selling Models
4. Hero Vida : 19,074 units (10.36% share | -17.06% MoM)
Aggregates the entire VX2 series, led by the flagship Vida VX2 Plus (10,251 units) and the Vida VX2 Go 3.4 (5,292 units). Features dual removable batteries (up to 4.4 kWh for 187 km IDC range) aimed at urban apartment dwellers, backed by flexible Battery-as-a-Service (BaaS) options.
5. Ola S1 : 13,221 units (7.18% share | -0.66% MoM)
Consolidates all S1 variants, led by the mass-market Ola S1X 4kWh Gen 3 (6,745 units), S1X 3kWh Gen 3 (1,770 units), and S1X 2kWh Gen 3 (1,101 units), alongside the premium S1 Pro Gen 2/3 series. Built on Ola's Gen-3 chassis architecture to keep entry prices aggressive against 110cc ICE commuters.
6. TVS Orbiter : 12,258 units (6.65% share | -11.51% MoM)
Includes the Orbiter V2 (10,983 units) and Orbiter V1 (1,275 units). Designed for the sub-₹1 lakh utility and commercial commuter space, featuring a 3.1 kWh battery (158 km IDC range), 14-inch front alloy wheels, a 34-liter boot, and an extended 845 mm dual seat.
7. Ampere / Greaves Series: 8,615 units (4.68% share | -14.97% MoM)
Combines the Ampere Magnus line (Magnus FE13A at 4,050 units and RD13A at 1,934 units) with the family-focused Ampere Nexus EX/ST series, driving Greaves' presence in Tier-2 and Tier-3 regional hubs.
8. Ather 450 Series: 6,522 units (3.54% share | +6.59% MoM)
Consolidates Ather’s flagship sports-scooter platform, including the 450X R35 (4,626 units), 450S R35 (795 units), 450S LR, and 450 Apex. Recorded positive MoM growth (+6.59%) driven by enthusiast demand for performance-oriented handling.
9. River Indie : 5,187 units (2.82% share | -14.05% MoM)
Comprises the Indie-G3 utility scooter. Positioned as the "SUV of Scooters," offering 43 liters of under-seat boot space, 12 liters of glovebox storage, pannier mounts, and 14-inch wheels for heavy-duty daily hauling.
10. Bajaj Chetak C25 Series: 3,524 units (1.91% share | -20.13% MoM)
Consists entirely of the entry-level Chetak C25 01 trim. Serving as Bajaj's budget entry-level offering, it utilizes a smaller 2.5 kWh battery pack designed for price-sensitive urban commuters transitioning into the Chetak ecosystem.
August Top 10 Sales Summary
To comment and participate in discussion Click Here
Recent Articles
Trending Articles
Kerala Makes EVs More Affordable: Revised Road Tax Structure to Accelerate Adoption
India Car Sales by Fuel Type — March 2026: EV Share Hits New High, CNG Surges, Petrol Loses Ground
No Fire Safety Certificate Will Be Declined Over EV Chargers, Says Haryana Fire Department
Haryana Releases Draft Fire Safety Guidelines for EV Charging